I’ve spent enough years working on homes across different climates to recognize a pattern that most homeowners miss until it’s too late. The properties that weather storms, floods, and temperature swings with minimal damage aren’t necessarily the newest or the most expensive. They’re the ones where someone made deliberate choices about drainage, materials, and structural protection years before the crisis arrived. The math on this is straightforward once you stop looking at climate resilience as an environmental gesture and start seeing it as a financial decision.
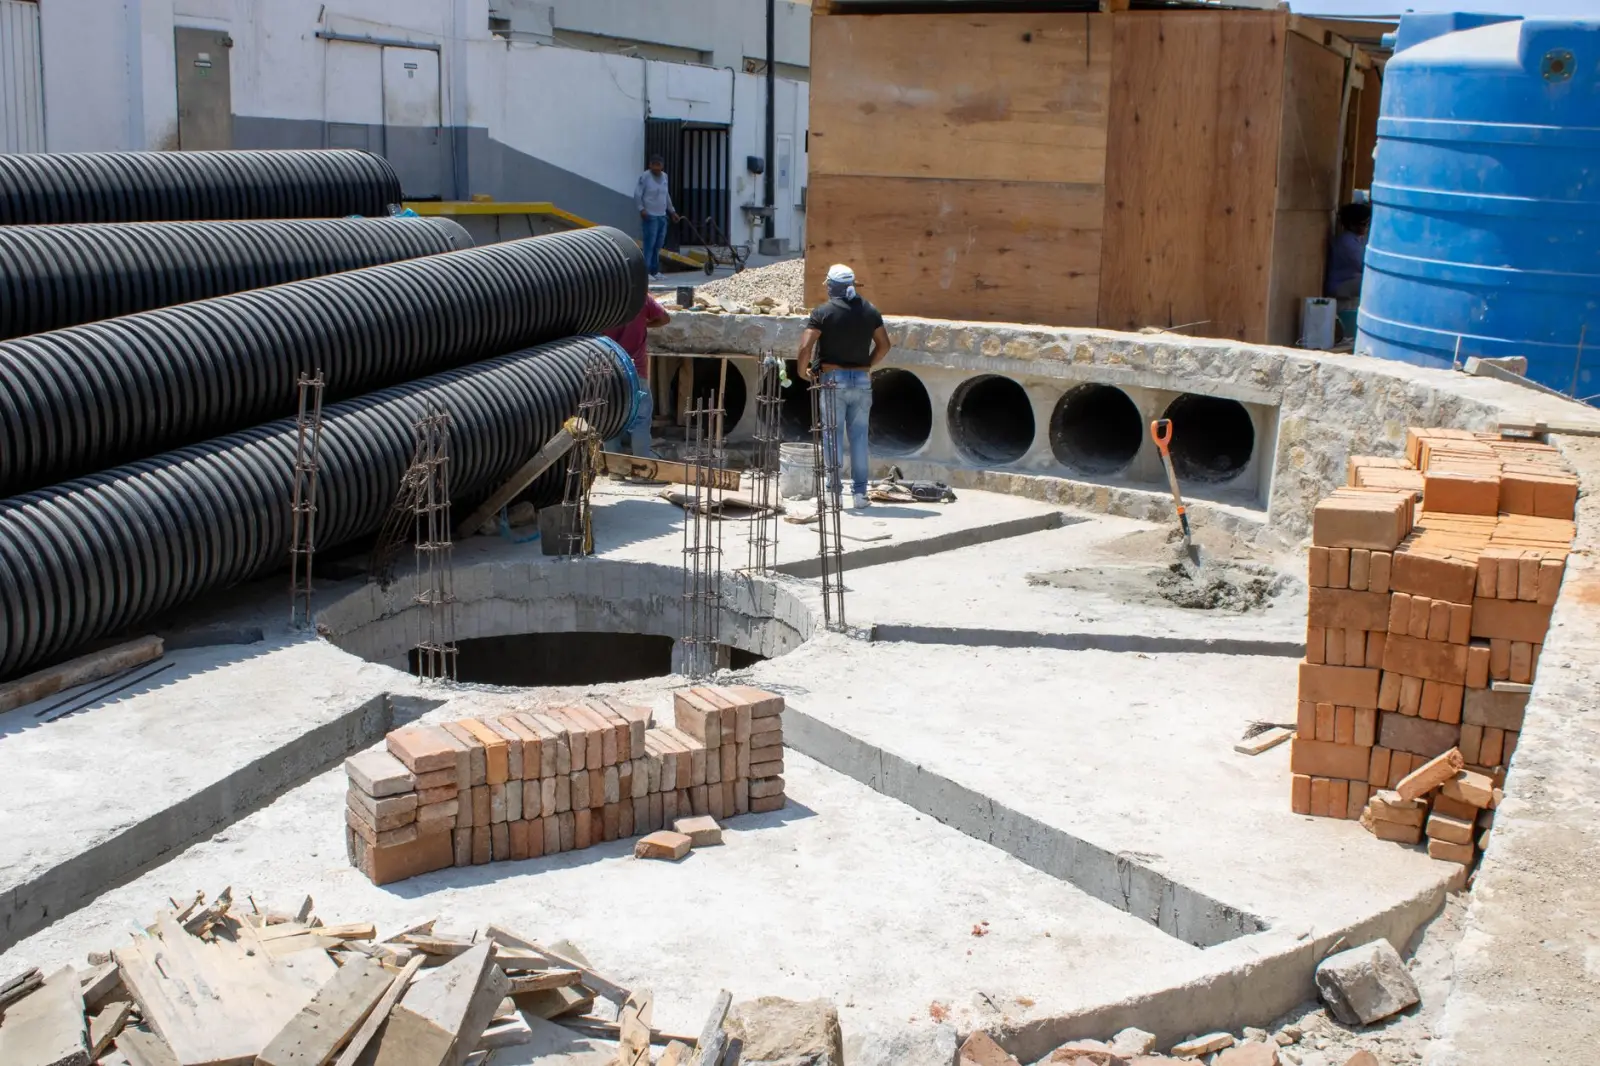
The economic argument for climate resilience in residential settings rests on a simple principle: prevention costs less than repair. I’ve watched homeowners spend $3,000 to $5,000 on basement waterproofing or foundation drainage work, then avoid $40,000 to $80,000 in water damage remediation during a heavy rain event. I’ve seen metal roofing installed at a 20 to 30 percent premium over asphalt, then hold up through hail storms that destroy conventional roofs in neighboring properties. These aren’t edge cases. They’re predictable outcomes that repeat across regions and property types.
The Insurance and Liability Layer
One of the most tangible economic signals is what happens with insurance. Carriers have been quietly tightening underwriting criteria for years, and they’re doing it based on climate exposure data, not guesswork. Homes in flood-prone zones without mitigation measures face higher premiums, coverage denials, or outright non-renewal. A property with proper grading, sump pump systems, and elevated utilities often qualifies for better rates. The difference between a standard policy and a high-risk policy can be $1,500 to $3,000 annually for a single home.
I’ve also noticed that insurers now offer explicit discounts for specific resilience measures. Impact-resistant windows and doors, roof reinforcement, backup power systems, and fire-resistant landscaping can reduce premiums by 10 to 25 percent depending on the carrier and the specific threat profile. Over a 20-year ownership period, those reductions compound into real money. A homeowner saving $200 per year on insurance through resilience upgrades recovers a $4,000 investment in less than a decade, before factoring in avoided claims and deductibles.
Material Longevity and Replacement Cycles
Climate resilience often means choosing materials that last longer under stress. This is where the economics become less obvious but more powerful. Standard asphalt roofing typically needs replacement every 15 to 20 years in moderate climates. In areas with temperature swings, UV exposure, and storm activity, that cycle compresses to 12 to 15 years. Metal roofing, by contrast, often lasts 40 to 50 years in the same conditions. The upfront cost is higher, but the total cost of ownership over 50 years heavily favors the durable option.
The same pattern applies to siding, windows, and exterior doors. Vinyl and fiber cement that can handle freeze-thaw cycles and UV degradation cost more initially but avoid the premature replacement cycles that plague cheaper alternatives. I’ve seen vinyl siding fail in 10 years in certain climates, while quality fiber cement survives 30 years with minimal maintenance. The homeowner who spent 40 percent more upfront on the better material ends up spending less overall.
Energy Efficiency as Resilience
There’s a direct economic connection between climate resilience and energy costs that often gets overlooked. Homes designed to handle temperature extremes – with proper insulation, air sealing, and thermal mass – use less heating and cooling energy regardless of the weather. During extreme heat or cold events, these homes also maintain livable conditions longer if utilities fail, reducing reliance on backup power or emergency accommodation.
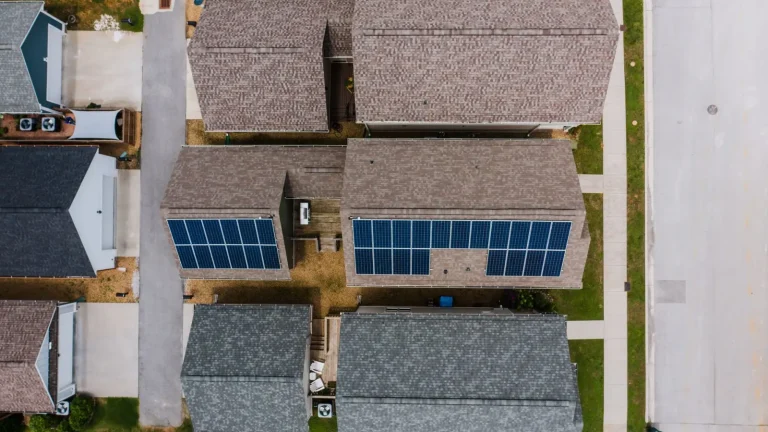
The numbers here are substantial. A home with poor insulation and air leaks might spend $2,500 to $4,000 annually on heating and cooling in a variable climate. The same home upgraded with modern insulation, sealed ductwork, and efficient windows might drop to $1,500 to $2,500. Over 20 years, that’s $20,000 to $40,000 in avoided energy costs. Add in resilience benefits during outages or extreme weather, and the financial case becomes difficult to argue against.
Property Value and Resale Economics
Buyers increasingly factor climate risk into their purchasing decisions. Properties with documented resilience measures – flood mitigation, storm-resistant construction, backup power, water storage – command better prices or sell faster in competitive markets. I’ve observed this most clearly in areas that have experienced recent flooding or storms. Post-event, homes with visible resilience features move quickly, while comparable properties without them sit longer or sell at discounts.
This isn’t speculation. Appraisers now incorporate climate risk into property valuations, and lenders are beginning to adjust financing terms based on resilience factors. A property that can demonstrate reduced climate risk through concrete improvements becomes a lower-risk asset in the eyes of the market. Over a 10 to 30-year holding period, this translates into better equity retention and appreciation.
Hidden Costs of Inaction
What rarely gets quantified is the cost of doing nothing. When a homeowner defers drainage improvements, skips roof maintenance, or ignores foundation issues, they’re not avoiding costs – they’re deferring them at a premium. A small water intrusion today becomes mold remediation, structural damage, and potential health issues later. A minor roof leak becomes attic damage, insulation failure, and compromised structural integrity.
I’ve also seen the ripple effects. One property with poor drainage affects neighboring properties. Deferred maintenance on one home can trigger insurance claims on adjacent properties, leading to rate increases across the block. The economic externalities of climate vulnerability extend beyond individual properties.
The economic case for climate resilience isn’t about virtue or environmental responsibility. It’s about recognizing that weather and climate variability are constants in residential property ownership. The question isn’t whether to invest in resilience, but when. Early investment spreads costs over time, allows for planned upgrades rather than emergency repairs, and captures the compounding benefits of lower insurance, reduced energy use, and avoided damage. Properties built or upgraded with resilience in mind consistently outperform those that treat climate as an afterthought, and the gap widens with each passing year.